1. Create or synchronize
Start with a QBO customer, invoice, amount, due date, line-item summary and accounting dimensions such as class, location or subsidiary.
Connect digital invoices to Request for Payment, payer choice, hosted payment pages and accounting reconciliation—across mobile, email, SMS, text and QR-code experiences.
Explore Today PaymentsProduct availability, payment timing, network reach, aliases and integrations depend on participating financial institutions, providers, underwriting and configuration.
Real-time settlement can shorten the movement of money to seconds, but speed alone does not close an invoice, identify a customer or reconcile a deposit. The future of transaction banking depends on connectivity, clean data and orchestration: the ability to connect an invoice, a digital request, a payer’s decision, a completed payment and the accounting record.
Today Payments brings these parts together through integration-ready workflows for QuickBooks Online, Request for Payment (RfP™), recurring billing, batch operations, hosted payment pages and multiple payment choices. The merchant is the Payee (Creditor); the customer is the Payer (Debtor). The payer reviews the request and chooses how and when to pay, subject to the options offered by the merchant and the payer’s financial institution.

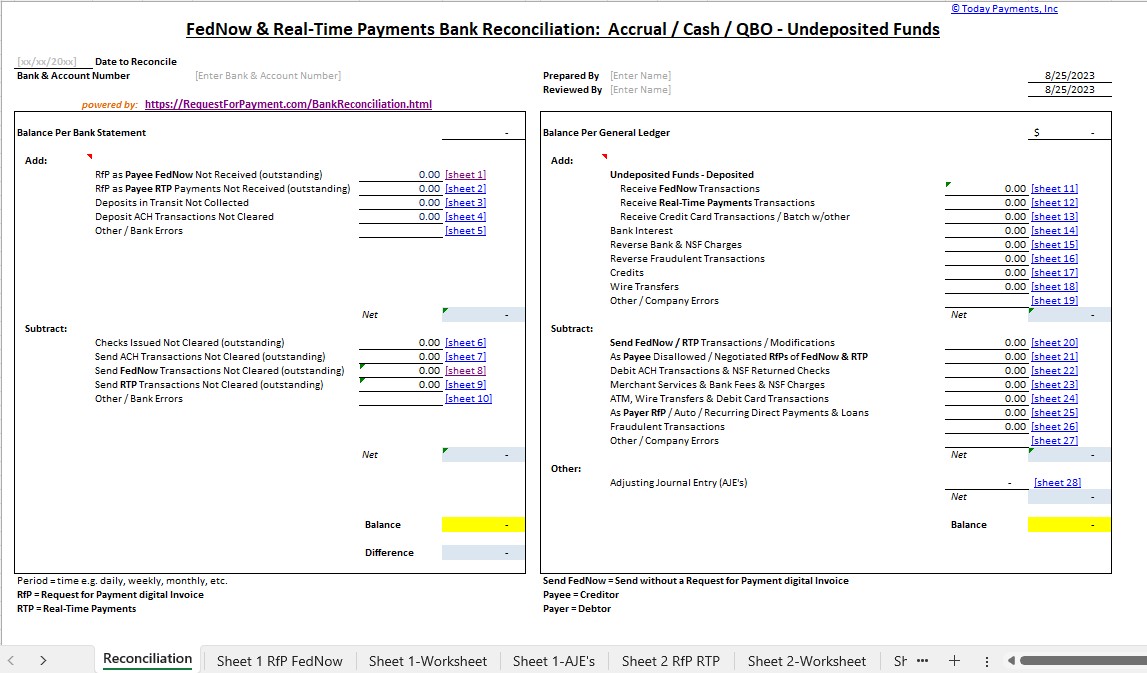
To support merchants and finance teams of all sizes, TodayPayments.com offers free downloadable templates, including:
A connected payment model begins with an invoice created or synchronized through QuickBooks Online. Today Payments can transform approved invoice data into a payment-request workflow and present it through mobile, email, SMS, text or a Quick Response Code (QR code). The request can route the payer to a secure Dashboard Hosted Payments Page that displays the invoice, merchant identity, amount, due date and available payment choices.
The hosted page becomes the decision layer—not the settlement network. Depending on eligibility and configuration, the payer may choose a FedNow-enabled instant credit transfer, ACH, a card, buy now/pay later, customer financing or another supported method. Each method has different authorization, timing, finality, dispute, return and fee characteristics.
Start with a QBO customer, invoice, amount, due date, line-item summary and accounting dimensions such as class, location or subsidiary.
Check customer identity, amount, currency, duplicate references, bank eligibility and delivery permissions before sending a request.
Map invoice data into the required RfP and provider format, assigning stable message, transaction and end-to-end identifiers.
Notify the payer through a supported bank channel or direct them to a secure hosted page using an authenticated link or QR code.
The payer reviews the request and authorizes an eligible payment through its financial institution or selected payment provider.
Match confirmed payment events to the invoice, apply deposits to the correct entity or account, and update QBO status and reporting.
Integration-ready means the data model and workflow are designed to connect with QBO. Production use requires an authorized application, supported API scopes, customer consent, testing and an active service configuration.
A Dashboard Hosted Payments Page can provide more detail than an RfP notification alone. It may display invoice documents, line items, purchase-order references, service dates, merchant contact information, discounts, payment-plan terms and the available payment methods. It can be hosted on a merchant-controlled domain or through a Today Payments hosted-page service, subject to security and configuration requirements.
Each division, subsidiary, franchise, location or brand can be associated with an internal merchant account or MID. Routing rules can then map the hosted page and invoice to the intended settlement account. These are platform-level identifiers and instructions; they are not identifiers issued by the FedNow Service. The receiving bank account and financial institution must be eligible for the selected rail.
Data hygiene is essential. The merchant legal name, DBA, invoice entity, settlement account, alias, customer reference and QBO company must remain consistently mapped. A clean master record helps prevent misdirected deposits, duplicate requests, orphaned payments and cross-entity reconciliation errors.
A verified phone number, email address or other proxy can create a friendlier payer experience and reduce the need to expose complete bank coordinates in the presentation layer. The alias must resolve through a supported directory or participating provider to the correct payee relationship. It does not eliminate the underlying bank-account and routing data needed by the financial institutions to settle a payment.
Today Payments can organize multiple aliases and associate each with an internal MID, business unit, hosted page and eligible deposit account. Because alias capabilities are not universal, availability must be confirmed for each bank, credit union, directory and payment rail. Strong controls should include alias verification, change approval, confirmation notices, tokenization and protection against business-email-compromise fraud.
A standing approval is a payer’s documented authorization for future transactions that meet defined conditions. Those conditions should identify the merchant, permitted amount or maximum, frequency, start and end dates, notification rules, funding account and cancellation process. A “set it and forget it” experience should still provide transparency, security and a way for the payer to manage the arrangement.
An RfP is a non-value message—it requests payment but does not debit an account. A FedNow payment is an instant credit transfer initiated through the payer’s financial institution, not a merchant-initiated debit. Automated recurring experiences require the payer’s provider to support the authorization and initiation model; a merchant cannot assume that every RfP will be paid automatically.
A business can upload or schedule a collection of invoice requests as a batch at the orchestration layer. Each accepted instant payment is nevertheless processed as an individual transaction with its own identity, screening, response and settlement result. A batch may therefore produce mixed outcomes: paid, pending, rejected, expired, failed validation or requiring review.
This distinction matters for QBO. The source batch should remain traceable, but accounting should post and reconcile each confirmed payment separately or through a controlled deposit grouping. Never mark an entire batch paid merely because the source file was accepted.
| Category | Representative data | Why it matters |
|---|---|---|
| Message identity | Message ID, creation time, request ID, instruction ID, end-to-end ID | Prevents duplicates and supports full lifecycle traceability |
| Payee (Creditor) | Legal/display name, account or supported alias, servicing institution | Identifies who requests and receives payment |
| Payer (Debtor) | Name, account relationship or supported proxy, payer institution | Routes the request to the intended customer |
| Amount and timing | Amount, currency, requested execution date, due date, expiry | Defines the requested obligation and action window |
| Invoice context | QBO invoice ID, invoice number, customer ID, PO, line-item summary | Supports review, cash application and audit |
| Remittance | Structured references and permitted unstructured text | Links the request and payment to the receivable |
| Presentation | Tokenized HTTPS link, QR-code token, hosted-page reference where permitted | Gives the payer secure access to expanded details and choices |
| Recurring controls | Mandate/consent reference, maximum, frequency, notice and expiry | Documents the approved recurring-payment boundaries |
| Accounting dimensions | Company, class, location, department, subsidiary, MID, deposit account | Directs posting and reconciliation to the correct books |
| Status and audit | Created, sent, delivered, viewed, responded, paid, expired, exception | Separates communication status from confirmed settlement |
Mobile, email, SMS, text and QR-code presentation for supported use cases.
Eligible real-time payments, ACH, cards, BNPL and financing options from one hosted experience.
Consent references, limits, schedules, notifications and cancellation workflows.
CSV/Excel intake, XML or JSON transformation, per-item validation and exception reporting.
Rules for entity, division, MID, alias, hosted page and eligible settlement account.
Integration-ready customer, invoice, payment, deposit, fee and reconciliation mappings for QBO.
| Format | Appropriate role | Important limitation |
|---|---|---|
| Excel / CSV | Merchant upload, operations review, batch intake and exception export | Not itself a FedNow network message; must be validated and transformed |
| JSON | API payloads between QBO, hosted pages, orchestration services and webhooks | Provider-specific schema; not the native FedNow wire format |
| XML | Serialization used by ISO 20022 messages and some bank interfaces | Valid XML is not necessarily valid for a specific network implementation |
| ISO 20022 | Structured financial messaging, including payment requests, responses and credit transfers | The exact FedNow usage guideline controls required elements, versions and restrictions |
| QBO API objects | Customers, invoices, payments, deposits and related accounting records | Require authorized API access, consent and mapping to payment-domain data |
The standard ISO 20022 unstructured-remittance element is commonly defined with a maximum length of 140 characters, not 145. If Today Payments accepts a 145-character input field, the platform should validate, shorten or map it into permitted fields before producing the network message. A hosted-page link should be concise, tokenized, HTTPS-secured and allowed by the receiving implementation; do not assume every bank channel will display or activate a hyperlink.
A minimum production RfP is not defined by a generic checklist alone. The current FedNow implementation guide determines which elements are mandatory, conditional or prohibited. At a practical level, an implementation normally needs the following groups:
| Data group | Practical minimum information |
|---|---|
| Business Application Header | Sender, receiver, business-message ID, message-definition ID, service ID and creation time as required. |
| Group header | Unique message ID, creation date/time, initiating party and transaction count where applicable. |
| Payment information | Payment-information ID, payment context, requested date/time and routing context. |
| Transaction identification | Instruction ID and/or end-to-end ID plus a unique request reference. |
| Amount | Requested amount and supported currency—ordinarily USD for domestic FedNow transactions. |
| Parties | Creditor/payee and debtor/payer identity data required by the use case. |
| Agents and accounts | Servicing financial institutions plus account or supported proxy information. |
| Remittance | Invoice or obligation reference using permitted structured and/or unstructured data. |
| Controls | Expiry, purpose, requested response and conditional data required for the implementation. |
ISO’s catalogue identifies pain.013 as the Creditor Payment Activation Request and pain.014 as its status report. Version numbers evolve. The associated funds movement uses a separate customer-credit-transfer message; an RfP response is not proof that settlement occurred.
An integration-ready workflow can synchronize approved QBO customer and invoice data, create a digital Request for Payment, present recurring-payment terms and return confirmed payment information for cash application. The payer’s provider must support the authorization model, and each settled payment should remain traceable to its invoice and consent reference.
A merchant can upload invoice data in CSV or Excel, while an orchestration service validates the records and converts eligible transactions to the exact ISO 20022 or provider format required by a participating institution. File acceptance does not equal payment; every request and resulting credit transfer needs its own status and reconciliation outcome.
A verified phone or email alias may be used in supported payment directories and presentation experiences, reducing the need to expose complete bank coordinates to the payer. The alias must still resolve securely to an eligible account relationship, and availability varies by bank, credit union, network and provider.
A Dashboard Hosted Payments Page is a secure destination where a payer can review invoice details and select an eligible payment method such as a real-time credit transfer, ACH, card, BNPL or customer financing. The page can preserve a consistent customer experience while Today Payments routes accounting and status data to the correct merchant entity and deposit workflow.
Clean identifiers make it possible to connect the payer, payee, invoice, RfP, payment confirmation, deposit account and QBO record without ambiguity. Strong validation and master-data controls reduce duplicate requests, misrouted funds, unidentified deposits and costly manual investigation.
Today Payments helps merchants move beyond disconnected invoices and payment links. Bring together integration-ready QuickBooks Online data, recurring and batch request workflows, hosted payment pages, alias-based presentation, multi-account routing and reconciliation intelligence.
Give customers a clearer way to review what they owe and choose how to pay. Give finance teams cleaner data, stronger visibility and a reliable path from invoice to confirmed deposit.
Build Your Connected Payment Workflow
Disclosure: Today Payments, Inc. is a financial-technology and merchant-services company, not a bank, the Federal Reserve or the FedNow Service. FedNow® is a registered service mark of the Federal Reserve Banks. QuickBooks is a trademark and service mark of Intuit Inc. This page does not imply endorsement, certification or affiliation. Availability, timing, finality, returns, limits, pricing, aliases, recurring features and integration functions depend on the participating financial institution, provider, payment method and applicable rules.